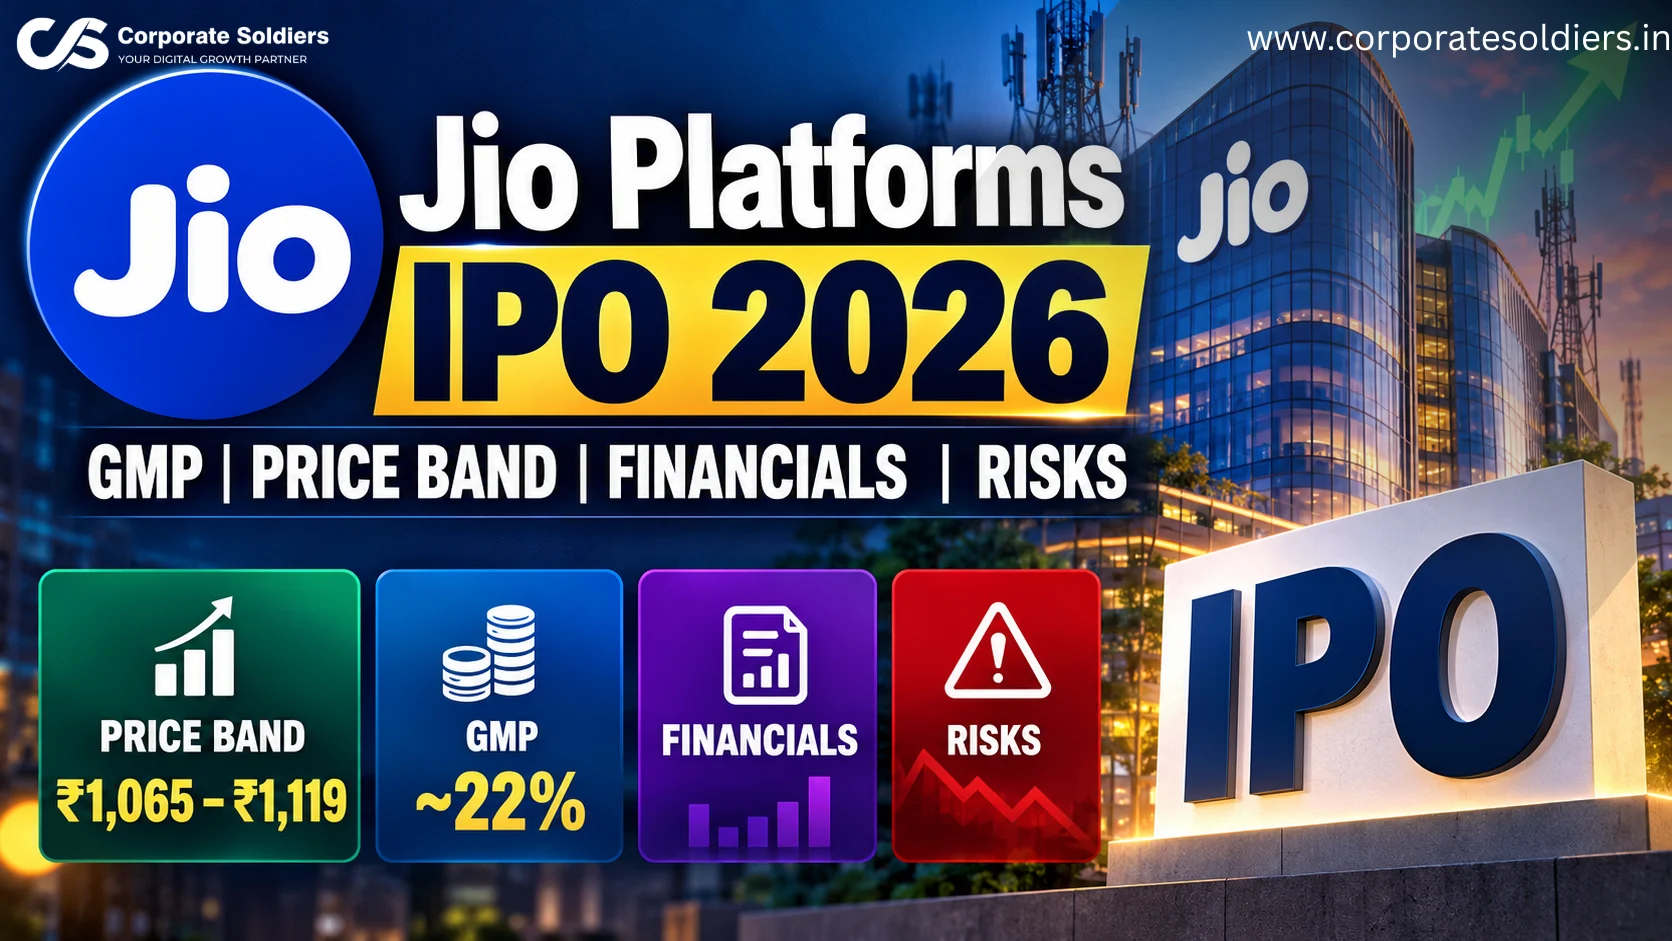
The Jio Platforms IPO is a ₹30,213 crore fresh issue priced at ₹1,065–₹1,119 per share. Jio Platforms reported FY2026 profit after tax (PAT) of ₹30,049 crore, but its valuation of approximately 33 times pre-issue earnings and its dependence on a single major subsidiary deserve careful consideration. The grey market premium (GMP) may indicate listing sentiment, but it does not establish fair value or guarantee returns. Investors should assess the company’s financial performance, capital efficiency, business risks and investment horizon before deciding whether to apply.
Jio Platforms IPO: Key Details at a Glance
- Price band: ₹1,065–₹1,119 per share
- Lot size: 12 shares
- Minimum investment: ₹12,780 at the lower band and ₹13,428 at the upper band
- Issue size: Up to ₹30,213 crore at the upper price band
- Issue type: Fresh issue of up to 27 crore shares, with no offer for sale (OFS)
- Subscription dates: October 21–23, 2026
- Tentative listing date: October 28, 2026
- Reported GMP: Approximately ₹250, or 22%, around October 22, 2026
The issue details and GMP above reflect the reporting available for October 22, 2026. GMP is unofficial and changes frequently. Allotment and listing dates remain subject to official confirmation.
Jio Platforms is attracting attention because of its large customer base, expanding revenue and position in India’s digital economy. However, a strong business does not automatically make its IPO attractive at every valuation. The key question is whether the company’s future earnings and cash flows can justify the price investors pay.
Jio Platforms IPO Details: Price Band, Lot Size and Dates
Jio Platforms Limited is offering shares through a book-built IPO. The issue is entirely a fresh issue, meaning the company receives the proceeds rather than existing shareholders selling their shares through an OFS.
| IPO parameter | Details |
| Company | Jio Platforms Limited |
| Price band | ₹1,065–₹1,119 |
| Lot size | 12 shares |
| Minimum investment at lower band | ₹12,780 |
| Minimum investment at upper band | ₹13,428 |
| Retail bidding limit | ₹2 lakh |
| Employee discount | ₹54 per share, subject to applicable terms |
| Shares on offer | Up to 27 crore |
| Issue size at lower band | Approximately ₹28,755 crore |
| Issue size at upper band | Approximately ₹30,213 crore |
| Implied post-issue market capitalisation | Approximately ₹10.3 lakh crore |
| Registrar | KFin Technologies |
| Proposed listing exchanges | NSE and BSE |
Important IPO dates
| Event | Date |
| Anchor investor bidding | October 19, 2026 |
| IPO opens | October 21, 2026 |
| IPO closes | October 23, 2026 |
| UPI mandate cut-off | 7:00 PM IST on October 23 |
| Expected allotment | Around October 26 |
| Tentative listing | October 28 |
The allotment and listing dates should be treated as tentative until confirmed by the registrar and stock exchanges.
Where will the IPO proceeds go?
The proceeds are intended primarily to prepay or repay specified borrowings of Reliance Jio Infocomm Limited (RJIL), along with general corporate purposes.
A fresh issue can support the company’s financial position when proceeds are used to reduce debt. However, investors should distinguish between the financial position of Jio Platforms as a holding company and the borrowings of its operating subsidiary.
Jio Platforms Business Model: Ownership, RJIL and Revenue Sources
Jio Platforms is a technology holding company built around digital services and connectivity. Its most significant operating business is Reliance Jio Infocomm Limited, the licensed telecom operator commonly known as Jio.
Ownership structure before the IPO
According to the supplied IPO research, the pre-issue ownership structure includes:
- Reliance Industries Limited: 66.43%
- Meta’s affiliate: 9.98%
- Google: 7.73%
The remaining ownership is held by other shareholders and investors.
How Jio generates revenue
Jio’s business model is based primarily on telecom connectivity and related digital services. Its activities include mobile subscriptions, data services, fibre broadband, fixed wireless access, enterprise connectivity and other technology offerings.
Its infrastructure combines network assets, spectrum, fibre, data systems and third-party infrastructure arrangements. This allows Jio to deliver connectivity at scale, although maintaining and upgrading a nationwide network requires significant investment.
As of June 30, 2026, RJIL served approximately 533.3 million customers, including 284.9 million 5G customers. JioFiber and JioAirFiber together had approximately 28.6 million customers, according to the supplied research.
Important data distinction: These customer figures relate to RJIL, not to Jio Platforms as a whole. The same distinction applies to the ARPU and churn figures discussed below.
Revenue concentration: An important risk
RJIL contributed 87.74% of Jio Platforms’ consolidated revenue in FY2026. The supplied prospectus analysis also attributes 93.76% of consolidated PAT to RJIL.
This concentration means that the operating performance of the telecom subsidiary has a substantial influence on the holding company’s financial results. Strong growth at RJIL can support Jio Platforms, but operational disruption, regulatory pressure or weaker customer economics at RJIL could also have a disproportionate impact.
The research further identifies Reliance Retail as the sole distributor of prepaid connectivity services, accounting for 77.08% of consolidated revenue in FY2026. Investors should assess the implications of this distribution arrangement and other related-party relationships disclosed in the prospectus.
Jio Platforms Financial Performance: FY2024 to FY2026
Jio Platforms’ historical financial performance shows growth in revenue and profit, higher ARPU and lower leverage. However, subscriber additions have fluctuated and returns on capital have declined.
| Financial metric | FY2024 | FY2025 | FY2026 |
| Customers (RJIL) | 481.8 million | 488.2 million | 524.4 million |
| Net customer additions | 42.5 million | 6.4 million | 36.2 million |
| Monthly ARPU, exit quarter | ₹181.70 | ₹206.20 | ₹214.00 |
| Revenue from operations | ₹1,09,558 crore | ₹1,28,218 crore | ₹1,46,885 crore |
| EBITDA margin | 50.16% | 50.05% | 51.91% |
| Profit after tax | ₹21,423 crore | ₹26,109 crore | ₹30,049 crore |
| Basic earnings per share | ₹23.96 | ₹29.21 | ₹33.63 |
| Cash CAPEX as a percentage of revenue | 48.84% | 34.53% | 23.27% |
| Net leverage | 0.88× | 0.71× | 0.36× |
| Return on capital employed (ROCE) | 12.83% | 12.50% | 10.76% |
| Monthly churn, exit quarter | 1.52% | 1.81% | 1.67% |
Source: FY2024–FY2026 historical figures from the supplied IPO research and prospectus analysis. CAPEX ratios are derived calculations. ARPU and churn figures are exit-quarter measures, not full-year averages.
Revenue and profit growth
Revenue from operations increased from ₹1,09,558 crore in FY2024 to ₹1,46,885 crore in FY2026, representing growth of approximately 34% over two years. The supplied research reports a revenue CAGR of 15.79%.
PAT increased from ₹21,423 crore to ₹30,049 crore over the same period, a rise of approximately 40%.
These figures indicate that the business expanded its revenue base and earnings. Investors should nevertheless assess whether future growth can be sustained and whether it translates into stronger free cash flow and returns on capital.
Subscriber growth has been uneven
Net customer additions fell from 42.5 million in FY2024 to 6.4 million in FY2025, before recovering to 36.2 million in FY2026.
The recovery is encouraging, but the variation highlights why investors should monitor customer additions, churn and market share rather than relying solely on the headline subscriber count.
ARPU has improved
Monthly ARPU rose from ₹181.70 in FY2024 to ₹214 in FY2026, an increase of approximately 17.8%.
Higher ARPU can support revenue growth when customers spend more on connectivity and digital services. However, future tariff increases must be evaluated alongside affordability, competition and customer retention.
Margins are strong, but capital returns need attention
EBITDA margin remained around 50–52% across the three financial years and reached 51.91% in FY2026. Net leverage declined from 0.88× to 0.36×, indicating a stronger leverage position under the reported measure.
However, ROCE fell from 12.83% in FY2024 to 10.76% in FY2026. This is an important consideration: higher operating margins and earnings do not necessarily mean that additional capital is generating better returns.
The supplied research also reports that EBITDA less cash CAPEX increased from ₹1,449 crore in FY2024 to ₹42,071 crore in FY2026. Investors should continue to monitor this measure alongside free cash flow, capital investment and debt.
Jio Platforms IPO GMP: What It Tells Investors
The grey market premium (GMP) is an unofficial premium at which IPO shares are reportedly traded in the grey market before listing. It reflects market sentiment but is not an official exchange price, a company valuation measure or a guaranteed listing outcome.
The supplied research records the following indicative readings:
| Date | Reported GMP | Approximate premium over ₹1,119 |
| October 9, 2026 | ₹167 | 15% |
| October 15, 2026 | ₹220 | 20% |
| Around October 22, 2026 | ₹250 | 22% |
GMP readings can vary by tracker and change within hours. The date and source of the latest quote should always be checked before publishing or relying on it.
Illustrative listing-gain calculation
Suppose the IPO lists at a price implied by a 20% premium over the upper issue price.
| Calculation | Amount |
| Upper issue price | ₹1,119 |
| Assumed GMP at 20% | ₹223.80 |
| Indicative listing price | ₹1,342.80 |
| Indicative gain per share | ₹223.80 |
| Indicative gain per lot of 12 shares | ₹2,685.60 |
| Gain if the shares list at the issue price | ₹0 |
This example is illustrative only. It assumes the stock lists at the price implied by the GMP and excludes applicable charges.
If the shares list at the issue price, there is no listing gain before costs. If they list below the issue price, an investor may incur a loss.
A high GMP can reflect strong demand or optimistic sentiment, but it does not establish that the IPO is fundamentally undervalued. Actual listing performance depends on market conditions, subscription demand, institutional participation and sentiment on listing day.
The key takeaway: GMP shows sentiment, not value.
Is the Jio Platforms IPO Valuation Fair?
At the upper price band of ₹1,119, the implied post-issue market capitalisation is approximately ₹10.3 lakh crore.
The supplied research calculates that the upper issue price is approximately 33 times FY2026 basic EPS of ₹33.63, using pre-issue figures. It also estimates the price at approximately three times FY2026 net asset value per share of ₹373.66.
These are calculations based on pre-issue figures. The issue of new shares can dilute per-share metrics, so investors should assess the final post-issue valuation using the appropriate share count and earnings basis.
How should investors evaluate the valuation?
Investors should consider several factors together:
- Earnings growth: Can Jio sustain profit growth over the next several years?
- Cash generation: Does the company generate sufficient cash after capital expenditure?
- Capital returns: Can ROCE stabilise or improve as capital intensity falls?
- Debt: Will repayment of specified borrowings improve financial flexibility?
- Revenue concentration: How much of the valuation depends on RJIL’s continued performance?
- Peer comparison: Is the valuation reasonable relative to comparable telecom businesses?
The prospectus identifies Bharti Airtel and Vodafone Idea as listed peers. A valid P/E comparison requires the same reporting date and consistent earnings methodology. Verified peer multiples should be taken from the prospectus’s “Basis for Issue Price” section rather than mixing figures from different dates.
A growing business can still produce disappointing shareholder returns if the IPO price already reflects optimistic expectations. Valuation therefore matters as much as business quality.
Three Metrics Long-Term Investors Should Track
The long-term investment case for Jio Platforms depends on whether the company can grow its customer base, increase revenue per user and manage capital expenditure efficiently.
1. Subscriber growth
Subscriber growth measures whether Jio continues to attract and retain customers. RJIL had 533.3 million customers as of June 30, 2026, after adding 8.9 million customers during that quarter.
Monthly churn was 1.67% in the FY2026 exit quarter, compared with 1.81% a year earlier.
Positive signals
- Consistent net customer additions.
- Stable or declining churn.
- Continued adoption of 5G, fibre broadband and fixed wireless services.
Warning signs
- Slowing subscriber additions.
- Rising churn.
- Loss of market share or weakening customer retention.
A large customer base is valuable only if the company can retain customers and monetise its services effectively.
2. ARPU growth
ARPU measures average monthly revenue per user. It rose from ₹181.70 in FY2024 to ₹214 in FY2026. Monthly data usage per customer also increased from 28.7 GB to 42.3 GB, according to the supplied research.
Future tariff increases and higher data consumption could support revenue growth. However, investors should check whether ARPU increases are sustainable and whether higher tariffs affect customer retention.
Positive signals
- ARPU rises while subscriber growth remains healthy.
- Higher data consumption supports recurring revenue.
- Better monetisation without a material increase in churn.
Warning signs
- Flat ARPU.
- Pricing pressure.
- Customer losses following tariff increases.
ARPU is an exit-quarter measure in the historical table, so it should not be confused with a full-year average.
3. CAPEX efficiency
Capital expenditure (CAPEX) includes investment in spectrum, fibre, network infrastructure and technology upgrades.
Cash CAPEX declined from 34.53% of revenue in FY2025 to 23.27% in FY2026. A ratio below 25% can serve as an analytical monitoring benchmark, but it is not a company commitment or a guarantee of improved performance.
Positive signals
- Capital intensity remains manageable.
- Cash flow improves as revenue grows.
- ROCE stabilises or increases.
Warning signs
- Heavy spending without sufficient improvement in profitability.
- Declining returns on capital.
- A new spectrum or 5G investment cycle pushes CAPEX higher.
Investors should assess CAPEX alongside free cash flow, net leverage and ROCE. A lower CAPEX ratio alone does not prove that the company is generating better returns.
Jio Platforms IPO Risks: What Investors Should Know
1. Dependence on RJIL
RJIL contributed 87.74% of consolidated revenue, 94.88% of EBITDA and 93.76% of PAT in FY2026, according to the supplied research.
Why it matters: Operational, financial or regulatory problems at RJIL could have a disproportionate effect on Jio Platforms’ overall performance.
2. Reliance on a single prepaid distributor
Reliance Retail is identified as the sole distributor of prepaid connectivity services, accounting for 77.08% of consolidated revenue in FY2026.
Why it matters: Dependence on one distribution relationship can create concentration and operational risks if the arrangement is disrupted.
3. Related-party arrangements
Jio has agreements with the promoter, Reliance Retail and other Reliance Group entities and shares the Jio brand with related businesses.
Why it matters: Investors should review the disclosed arrangements, contractual terms and related-party transactions to understand how these relationships may affect costs, operations and financial performance.
4. Licence and spectrum requirements
RJIL depends on telecom licences and access to spectrum. Renewal requirements and future spectrum acquisition can involve substantial costs.
Why it matters: Regulatory changes or difficulties securing necessary licences and spectrum could affect operating costs, network capacity and profitability.
5. Infrastructure concentration and network disruption
Jio relies on tower and fibre providers and other infrastructure and technology arrangements.
Why it matters: Provider concentration or network disruption could affect service availability, customer satisfaction and operating costs.
6. Technology and cybersecurity
The prospectus identifies technological obsolescence, cybersecurity and artificial intelligence or machine-learning-related risks.
Why it matters: Technology failures or security incidents can result in operational disruption, remediation expenses and reputational damage.
7. Valuation risk
At approximately 33 times pre-issue FY2026 EPS, the IPO price assumes that investors are willing to pay a substantial multiple of current earnings.
Why it matters: If earnings growth falls short of expectations, the valuation multiple may contract even if the business remains profitable.
8. Debt and capital allocation
The supplied research reports total borrowings of ₹70,781 crore at FY2026 year-end and ₹61,372 crore at June 30, 2026.
Why it matters: Investors should assess the debt position of the holding company and its subsidiaries, the use of IPO proceeds and whether future network investment generates adequate returns.
9. Regulation and satellite internet competition
Government decisions on tariffs, spectrum and licensing can affect the telecom sector. Satellite-based internet could also compete for certain broadband customers, especially in underserved areas.
Why it matters: These are relevant industry considerations, but they should be distinguished from the specific risk factors formally highlighted in the prospectus. Satellite connectivity could also create opportunities through partnerships and new services.
Should You Apply for the Jio Platforms IPO?
The IPO presents two different investment questions: whether the shares may deliver listing gains and whether the company can generate attractive long-term returns.
| Area | Key question | What to examine |
| Listing gains | Is market sentiment supportive? | Dated GMP and subscription figures |
| Subscriber growth | Are net additions and churn stable? | RJIL customer data |
| ARPU | Is monetisation improving without higher churn? | Quarterly ARPU trends |
| CAPEX and ROCE | Are investments generating adequate returns? | CAPEX-to-revenue ratio and ROCE |
| Leverage | Is debt manageable? | Net leverage and repayment plans |
| Concentration | Can you accept dependence on RJIL and Reliance Retail? | Prospectus risk factors |
| Valuation | Does the price fit your return expectations? | EPS, cash flow and comparable peers |
| Investment horizon | Are you seeking listing gains or long-term ownership? | Personal goals and risk capacity |
Short-term investors should recognise that GMP and subscription demand can change and do not guarantee a profitable listing.
Long-term investors should focus on sustainable earnings, customer growth, ARPU, capital efficiency, cash generation, debt and valuation.
This framework is intended to help readers evaluate the IPO; it is not a recommendation to apply or avoid it.
Jio Platforms IPO FAQs
1. What is the Jio Platforms IPO price band and lot size?
The price band is ₹1,065–₹1,119 per share, and one lot contains 12 shares. The minimum investment is ₹12,780 at the lower band and ₹13,428 at the upper band. Investors should verify the final issue terms before applying.
2. When does the Jio Platforms IPO close and list?
The IPO is scheduled to close on October 23, 2026, with the UPI mandate cut-off at 7:00 PM IST. Allotment is expected around October 26, and listing is tentatively scheduled for October 28. These dates remain subject to official confirmation.
3. What is the Jio Platforms IPO GMP today?
The supplied research records a GMP of approximately ₹250, or 22%, around October 22, 2026. GMP is an unofficial grey-market estimate that changes frequently and does not guarantee the listing price or returns. Always check the date and source of the latest reading.
4. Is the Jio Platforms IPO a fresh issue or an offer for sale?
It is a fresh issue of up to 27 crore shares, with no offer for sale. The proceeds are intended to prepay or repay specified borrowings of Reliance Jio Infocomm Limited and support general corporate purposes.
5. Is the Jio Platforms IPO suitable for long-term investors?
That depends on the price paid, future business performance, investment horizon and risk tolerance. FY2026 revenue was ₹1,46,885 crore and PAT was ₹30,049 crore, but the valuation is approximately 33 times pre-issue EPS and revenue is highly concentrated in RJIL. Investors should evaluate subscriber growth, ARPU, CAPEX efficiency, debt and valuation together.
6. What are the biggest risks in the Jio Platforms IPO?
The supplied prospectus analysis highlights dependence on RJIL, Reliance Retail’s role as sole prepaid distributor, related-party arrangements, licence and spectrum requirements, infrastructure-provider concentration, cybersecurity and valuation risk. Satellite internet competition and tariff regulation are additional industry considerations.
7. Why is CAPEX important for Jio Platforms?
Telecom operators require significant investment in spectrum, fibre, network equipment and technology. CAPEX efficiency indicates whether these investments generate adequate revenue, cash flow and returns on capital. A lower CAPEX-to-revenue ratio is encouraging, but investors should also monitor ROCE, leverage and future network requirements.
8. Does a high GMP guarantee listing gains?
No. GMP is unofficial and can change rapidly. Actual listing performance depends on market conditions, demand and investor sentiment. Shares may list below the issue price, resulting in a loss.
Conclusion: GMP Shows Sentiment, Fundamentals Determine Value
The Jio Platforms IPO combines a large customer base, rising revenue and profit, and declining leverage with a valuation that already reflects substantial expectations.
For short-term investors, GMP and subscription demand may provide clues about market sentiment, but neither guarantees listing gains. For long-term investors, the more important questions concern subscriber growth, ARPU improvement, CAPEX efficiency, ROCE, debt and valuation.
Jio’s financial growth is encouraging, but its dependence on RJIL and the decline in returns on capital deserve careful consideration. Investors should compare the IPO valuation with earnings and cash generation, read the prospectus and assess whether the potential returns justify the risks.
The bottom line: A strong business is not automatically a good investment at every price. GMP reflects sentiment; sustainable earnings growth, capital efficiency and valuation are more important for assessing long-term value.
Sources and methodology
- Jio Platforms Limited, Red Herring Prospectus and Abridged Prospectus dated October 14, 2026, available through the SEBI filings page.
- Jio Platforms official IPO investor relations.
- IPO price band, lot size, issue size and dates should be checked against the final prospectus and official exchange announcements.
- GMP readings are unofficial estimates reported by grey-market trackers and media sources; they are not official market prices.
- Derived figures, including CAPEX ratios, growth percentages and the approximate P/E multiple, are calculations based on reported financial data.
- Customer counts, ARPU and churn refer to RJIL. ARPU and churn figures are exit-quarter measures where specified.
Disclaimer: This article is for educational purposes only and is not personalised financial advice or a recommendation to subscribe to or purchase any security. Verify all terms in the final prospectus and exchange announcements before investing.
Source:
- https://m.economictimes.com/markets/ipos/fpos/jio-ipo-day-2-gmp-at-22-issue-subscribed-over-3-16-check-brokerage-views-and-key-details/articleshow/135106282.cms
- https://www.jio.com/about/investor-relations/ipo/
- https://www.reuters.com/world/india/indias-jio-platforms-targets-nearly-106-billion-valuation-ipo-sources-say-2026-10-09/
- https://www.sebi.gov.in/filings/public-issues/oct-2026/jio-platforms-limited-rhp_105274.html